Choosing the right insurance policy can feel confusing, especially if you are buying insurance for the first time. With so many plans, companies, and terms to understand, many people end up purchasing the wrong policy or paying for coverage they don’t actually need.
This guide explains everything in simple words—from understanding your needs to comparing policies, calculating premiums, checking claim settlement ratios, avoiding common mistakes, and answering frequently asked questions.
Why Choosing the Right Insurance Policy Matters
Insurance is meant to protect you and your family during difficult times. The right policy can help you:
- Protect your family’s future
- Save money during emergencies
- Avoid financial stress
- Get tax benefits
- Build long-term financial security
Buying insurance without proper research may result in:
- Paying high premiums
- Low claim amount
- Hidden exclusions
- Inadequate coverage
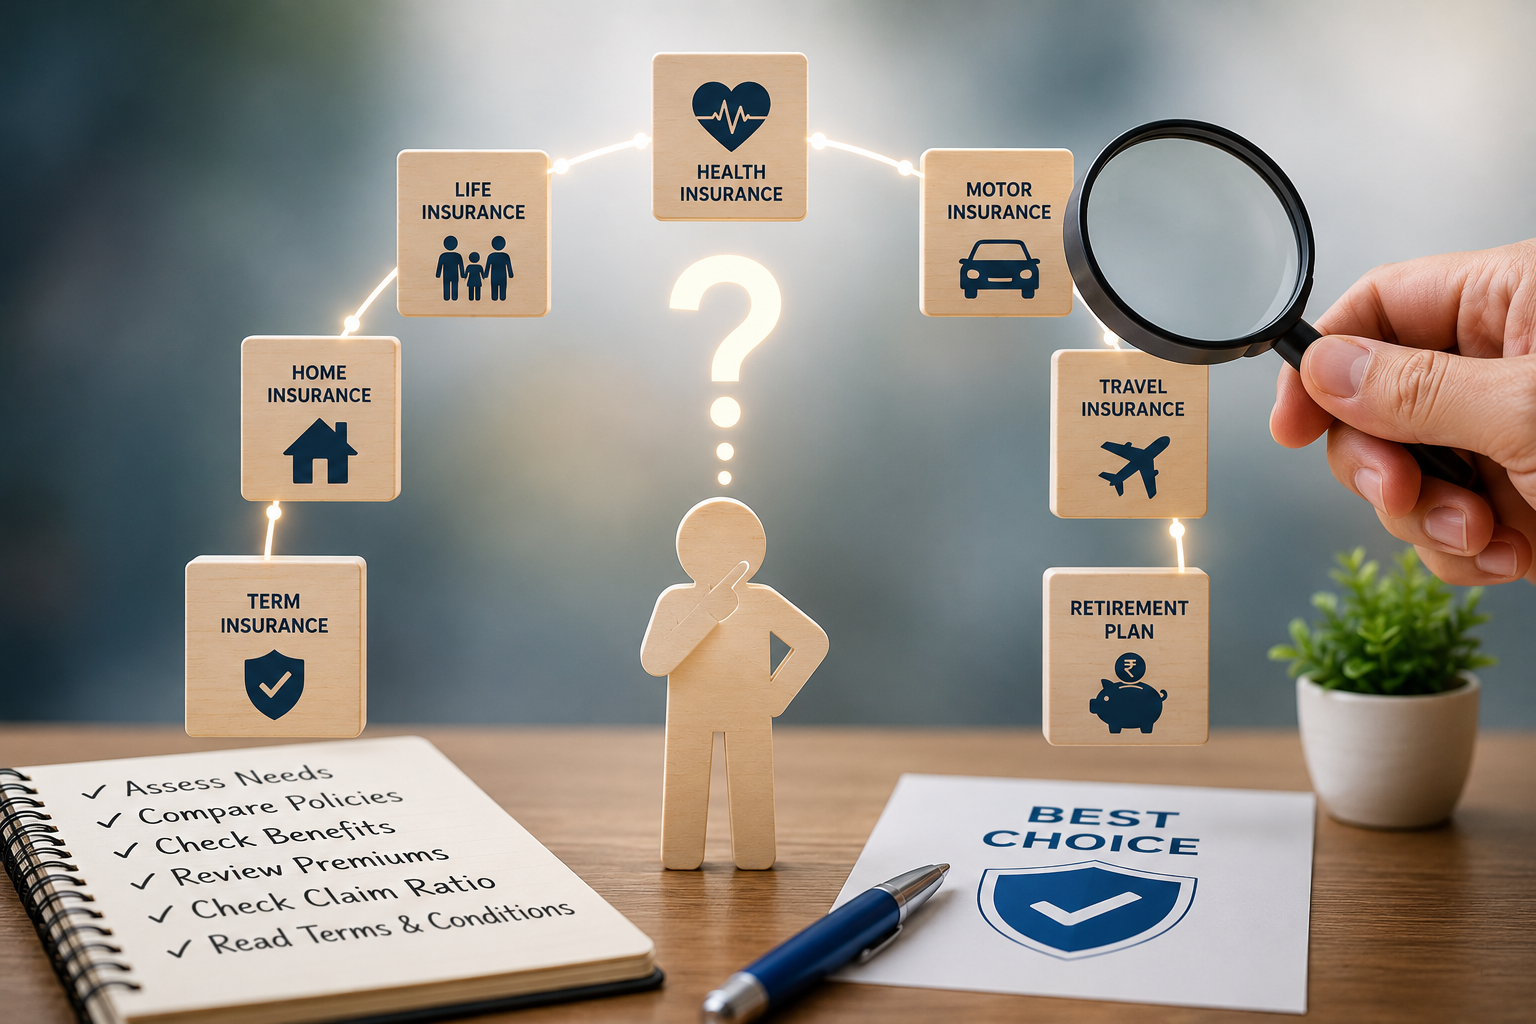
Step-by-Step Guide to Choosing the Right Insurance Policy
Step 1: Identify What You Want to Protect
First, ask yourself:
- Do I want health protection?
- Do I need life insurance?
- Do I own a vehicle?
- Do I travel often?
- Do I own a house?
- Do I have valuable gadgets?
Your needs decide which insurance policy is best.
Example
| Situation | Insurance Needed |
|---|---|
| Family depends on your income | Life Insurance |
| Medical expenses | Health Insurance |
| Own a bike/car | Motor Insurance |
| Frequent traveler | Travel Insurance |
| Home owner | Home Insurance |
Step 2: Decide the Coverage Amount
Coverage means the maximum amount the insurance company will pay.
Do not buy too little coverage just because the premium is cheaper.
Example
Suppose your family needs ₹50 lakh for future financial security.
Buying only ₹10 lakh life insurance may not be enough.
Similarly,
If hospital treatment can cost ₹8–10 lakh today, buying only a ₹2 lakh health policy may not provide adequate protection.
Step 3: Compare Different Insurance Companies
Never buy the first policy you see.
Compare:
- Premium
- Coverage
- Waiting period
- Exclusions
- Customer reviews
- Cashless hospitals
- Claim settlement ratio
- Add-on benefits
Comparison helps you get better value.
Step 4: Understand What Is Covered
Read the policy carefully.
For example, a health insurance policy may cover:
- Hospital expenses
- ICU charges
- Surgeries
- Day-care treatments
- Ambulance charges
- Pre and post hospitalization
Step 5: Understand What Is NOT Covered
Many claims get rejected because people don’t read the exclusions.
Common exclusions include:
- Cosmetic surgery
- Self-inflicted injuries
- Experimental treatments
- Pre-existing diseases during the waiting period
- Illegal activities
Always check the exclusions before purchasing.
Step 6: Check the Claim Settlement Ratio
One of the most important factors is the Claim Settlement Ratio (CSR).
What is Claim Settlement Ratio?
It shows how many claims an insurance company settles out of every 100 claims received.
Example
If a company receives:
100 claims
and settles
98 claims
then
Claim Settlement Ratio = 98%
A higher claim settlement ratio generally indicates a stronger track record of honoring claims.
Step 7: Check the Waiting Period
Many insurance policies have a waiting period.
For example:
Health insurance may have:
- 30-day initial waiting period
- 2–4 years for pre-existing diseases
- Waiting period for specific illnesses
Shorter waiting periods are generally better.
Step 8: Choose the Right Premium
Don’t buy insurance only because it has the lowest premium.
Instead, find the balance between:
- Affordable premium
- Adequate coverage
- Good benefits
Cheap policies often provide limited protection.
Step 9: Check Add-On Covers
Many insurers offer optional add-ons.
Examples:
For Health Insurance:
- Room rent waiver
- Critical illness cover
- Maternity cover
- OPD cover
For Car Insurance:
- Zero depreciation
- Engine protection
- Roadside assistance
- Return to invoice
These add-ons increase protection for a small extra cost.
Step 10: Read Customer Reviews
Look at:
- Claim experience
- Customer service
- Complaint handling
- Settlement speed
A slightly more expensive insurer with excellent service may be worth choosing over a cheaper one.
Factors to Compare Before Buying Insurance
| Factor | Why It Matters |
|---|---|
| Premium | Cost you pay |
| Coverage | Maximum protection |
| Claim Settlement Ratio | Reliability of claim payment |
| Waiting Period | Time before benefits start |
| Network Hospitals | Cashless treatment availability |
| Exclusions | What isn’t covered |
| Add-ons | Extra protection |
| Customer Reviews | Service quality |
| Renewability | Long-term protection |
| Tax Benefits | Savings under tax laws |
How Insurance Premium is Calculated
Insurance companies calculate premiums based on several factors.
Health Insurance
Premium depends on:
- Age
- Medical history
- Lifestyle
- Sum insured
- City
- Smoking habits
Life Insurance
Premium depends on:
- Age
- Income
- Occupation
- Health condition
- Smoking status
- Policy term
Car Insurance
Premium depends on:
- Vehicle age
- Model
- Engine capacity
- City
- IDV (Insured Declared Value)
- No Claim Bonus (NCB)
Example of Premium Comparison
| Coverage | Annual Premium (Approx.) |
|---|---|
| ₹5 lakh Health Insurance | ₹6,000–₹12,000 |
| ₹10 lakh Health Insurance | ₹9,000–₹18,000 |
| ₹1 Crore Term Insurance (Age 30) | ₹8,000–₹15,000 |
| Car Insurance | Depends on vehicle type and coverage |
Premiums are approximate and vary by insurer, age, location, and other risk factors.
Common Mistakes to Avoid
Many first-time buyers make these mistakes:
❌ Buying insurance only to save tax
❌ Choosing the cheapest policy
❌ Not reading exclusions
❌ Hiding medical conditions
❌ Buying insufficient coverage
❌ Ignoring waiting periods
❌ Not comparing multiple insurers
❌ Missing premium payment deadlines
❌ Forgetting to update nominees
Avoiding these mistakes can save you from claim rejection and inadequate coverage.
Tips for First-Time Insurance Buyers
- Start insurance at a younger age.
- Buy insurance according to your needs, not someone else’s recommendation.
- Compare at least 3–5 policies.
- Choose a trusted insurer with a good claim settlement record.
- Read the policy document carefully.
- Keep all documents safely.
- Review your insurance every few years as your income and family responsibilities change.
Frequently Asked Questions (FAQs)
1. Which insurance should I buy first?
Most people should start with health insurance and term life insurance (if they have financial dependents). If you own a vehicle, motor insurance is also essential and legally required.
2. What is the ideal health insurance coverage?
Many financial experts suggest choosing a sum insured that can comfortably cover treatment costs in your city and your family’s needs. The right amount varies based on age, family size, and healthcare costs.
3. Is a higher premium always better?
No. A higher premium may provide more benefits, but you should compare the coverage, exclusions, claim record, and overall value rather than focusing only on price.
4. Can I have multiple insurance policies?
Yes. You can hold multiple health or life insurance policies if they suit your financial needs and you disclose existing coverage when required.
5. What happens if I miss a premium payment?
Most policies offer a grace period. If the premium isn’t paid within that period, the policy may lapse, causing you to lose coverage.
6. What is a nominee?
A nominee is the person who receives the insurance benefits after the policyholder’s death, as per the policy terms.
7. Can I switch my insurance company?
Yes. In health insurance, you may be able to port your policy to another insurer while retaining certain benefits, subject to applicable rules and the new insurer’s acceptance.
Conclusion
Choosing the right insurance policy is not just about finding the lowest premium—it’s about ensuring you and your family have the protection you need. Start by understanding your goals, compare different policies carefully, review coverage and exclusions, check the insurer’s claim settlement record, and choose a plan that fits both your needs and your budget.
A well-chosen insurance policy offers financial security and peace of mind when you need it most.